CEA Group Global Strategy
The US$1 Billion Water-Treatment Pathway
A global strategy & sales plan to build a US$1bn water-treatment business in five years — delivering CEA's own Rev 11 target, honestly costed.
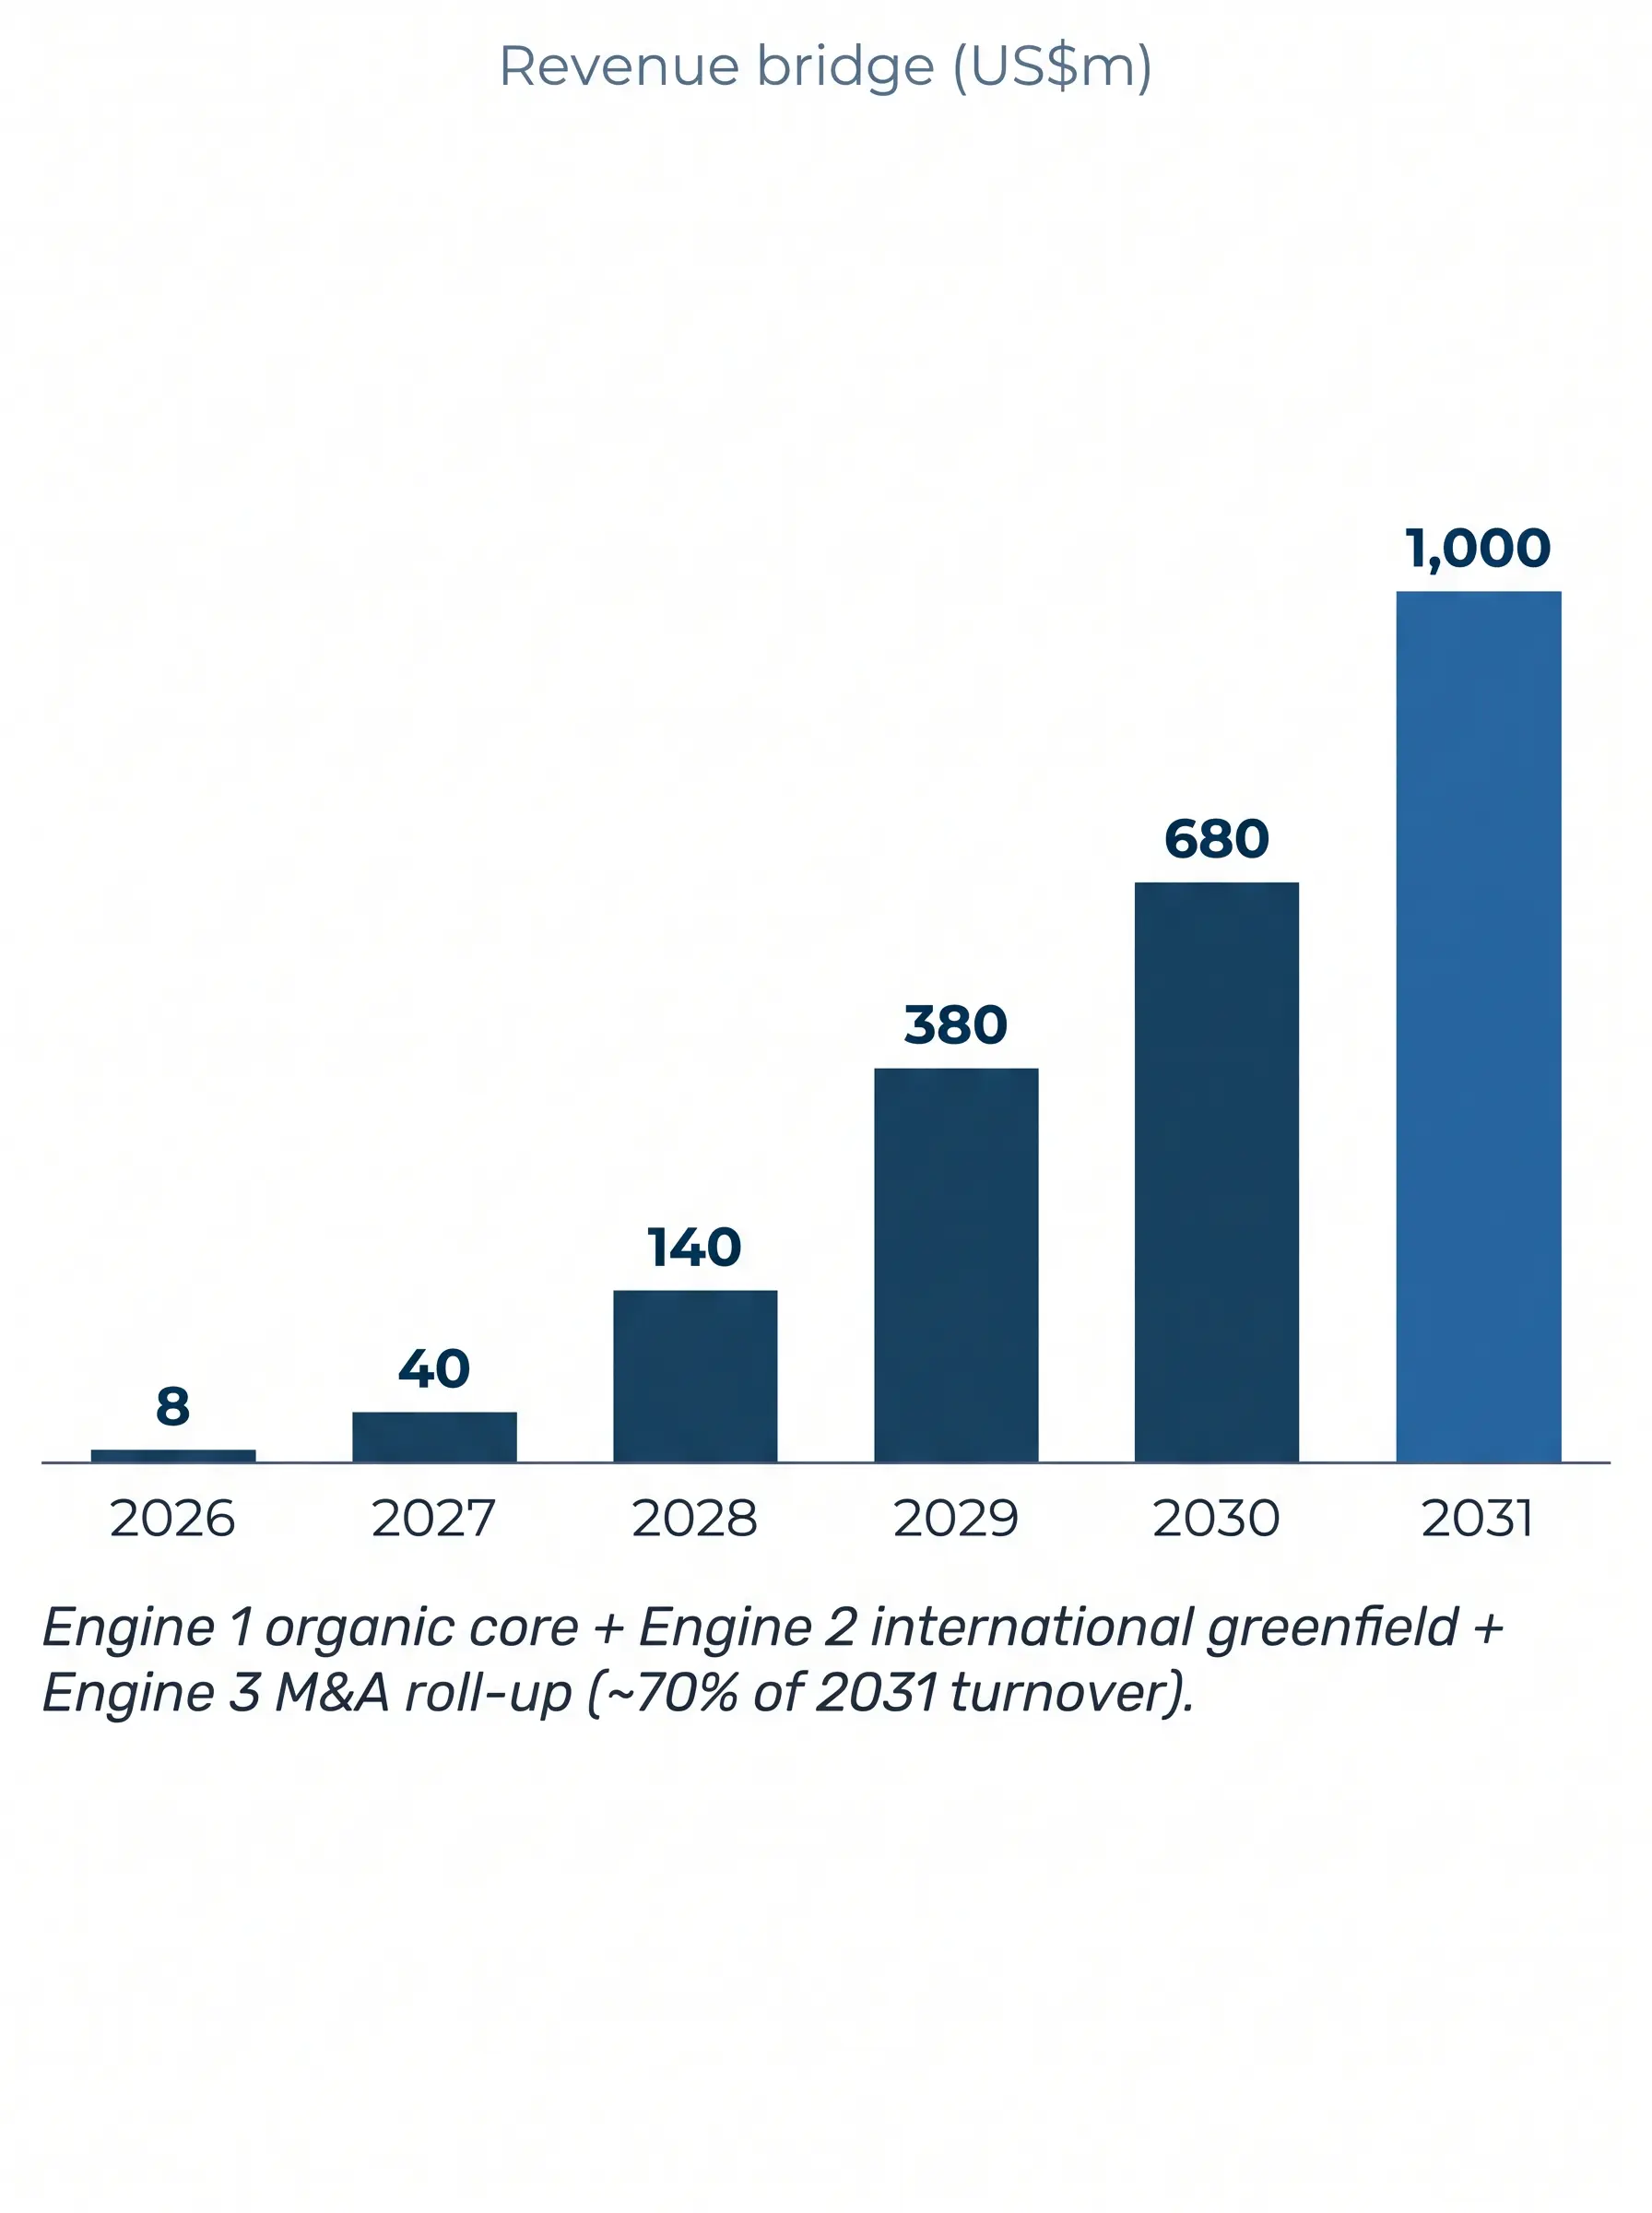
~US$8m
2026 base turnover (water-treatment led)
US$1.0bn
2031 target · CEA's own Rev 11 goal (>US$1bn)
~2.1%
of global chemicals market · meets >2% Rev 11 goal
~US$1.7bn
capital required · ~10–18 acquisitions
The central finding — US$1bn is not achievable organically
Growing from ~US$8m to US$1bn is a ~163% CAGR. The most aggressive credible organic plan tops out at ~US$150m by 2031 (already ~80% CAGR)
The market
US$37.1bn → US$46.6bn by 2029 · ~4.0% CAGR. A slow-growing, essential market — so US$1bn is a share-gain and consolidation play, not a growth-surfing one.
-
Industrial demand (power, oil & gas, mining, paper) leads — CEA's home turf.
-
Desalination & reuse grow fastest — fit for CEA's RO/ZLD offer.
-
Scale sits in North America (31%) & Asia-Pacific (fastest) — where CEA must acquire.
Stay an operator
~US$150–250m by 2031
Fundable from cash flow · low dilution · full control · lower risk. Strong, profitable, owner-led growth — but not US$1bn.
Become a consolidator
~US$1.0bn by 2031
Raise ~US$1.7bn (~55% equity / 35% debt / 10% cash) · ~10–18 acquisitions across 5 regions · meaningful dilution & shared control · moderate-high execution risk · strong reward. At ~16% EBITDA, EV ≈ US$1.92bn.
Recommendation
Begin as the base case — win the anchor recurring contracts and build the M&A / integration engine now and convert to the stretch pathway the moment a credible anchor capital partner is secured. CEA never bets the company on capital that has not arrived.
Five priorities
-
Win the anchor recurring contracts (Sasol, Eskom, Sappi/Mondi, mining, Aramco).
-
Stand up the M&A & integration engine — one ERP/CRM, procurement synergies, cross-sell — before scaling deals.
-
Secure an anchor capital partner — the binding constraint.
-
Build five regional platforms — SSA, Middle East, Asia-Pacific, North America, Europe.
-
Protect margin, cash & governance at every step (40% gross-margin floor).
Decisions the board must take
-
Endorse US$1bn (CEA's own Rev 11 target) as the five-year north-star via the operator-to-consolidator route.
-
Mandate the capital raise and agree limits on dilution and control.
-
Approve the M&A framework and form a Corporate Development / integration function.
-
Instruct Finance to validate numbers, margins & FX and build the monthly plan.
-
Lock the top 10–20 anchor accounts with written value cases.
Client is King. Sales are number one. Growth is only valuable when it is profitable, fundable and well-governed.
Our Mission: Empowering SME Water Businesses
A Global Focus on Growth
We target small and medium-sized businesses (SMEs) in the global water treatment industry to acquire, add value, and build them to get to the next level of business.
Ensuring Sustainability
We establish long-term viability through succession planning, robust management structures, sound corporate governance, and technical support.
Driving Local Impact
These businesses play a vital role in driving local innovation, reducing poverty, and creating jobs.
For opportunities please email: mna@ceagrp.com